
A first-time homebuyer in Malaysia should set a safe monthly repayment and cash reserve before viewing properties. A bank’s maximum approval amount shows borrowing capacity, while a personal budget shows what the household can sustain after groceries, transport, insurance, family commitments, and savings.
For a first time home buyer malaysia, the purchase price is only one part of the commitment. The buyer also needs funds for the deposit, legal work, stamp duty, valuation, moving, renovations, maintenance charges, quit rent, assessment tax, and emergency repairs. The First Home toolkit helps organise these decisions before house hunting begins.
The target is a home that leaves room for ordinary life and unexpected expenses. A written budget gives each property viewing a clear price ceiling and reduces the risk of paying a booking fee before financing and cash requirements are confirmed.
How Much House Can You Comfortably Afford?
A comfortable home budget starts with a repayment that fits income after existing debts and essential spending, with cash reserves left untouched. For anyone learning how to buy a house in malaysia, the calculation should cover loan capacity, upfront funds, and the recurring cost of ownership.
A household should test its budget against interest-rate changes and income interruptions. The financing guide and an affordability calculator can help turn income and commitments into a practical price range.
Calculate Your Debt Service Ratio and Safe Monthly Repayment
Banks assess the debt service ratio (DSR) by comparing monthly debt commitments with gross or net income under their own lending rules. Existing car loans, personal loans, credit-card balances, education loans, and other housing loans reduce the amount available for a new mortgage.
A buyer can use this sequence:
- Add every required monthly debt payment.
- Estimate the new home loan repayment using a conservative interest rate.
- Divide total monthly debt payments by the income figure used by the lender.
- Keep the personal housing budget below the bank’s maximum approval.
A repayment near 30% of monthly income gives the household more room for utilities, food, transport, insurance, and savings. The bank’s loan tenure, margin of financing, age limits, credit record, and documented income will determine the approved amount. Self-employed applicants should prepare consistent bank statements, tax documents, and business records.
Add Up the Cash Needed Before Signing
A buyer should prepare cash for the deposit and transaction expenses before committing to a property. A 90% financing margin leaves a 10% deposit, while a lower margin raises the required contribution.
The cash plan should include:
- Deposit or balance purchase price
- Sale and purchase agreement legal fees
- Loan agreement legal fees
- Stamp duty and loan-document charges
- Valuation fees for eligible properties
- Bank, registration, disbursement, and administrative charges
- Renovation, appliances, moving, and initial repairs
The actual amount depends on property price, transaction structure, lender, lawyer, and available exemptions or schemes. A current cost guide for Malaysian homebuyers provides a useful checklist, while a first-time buyer should confirm applicable relief directly with the lawyer and relevant agency before assuming a saving applies.
Build a Buffer for Ongoing Ownership Costs
A sustainable budget reserves money each month for costs that sit outside the loan repayment. Condo owners should allow for maintenance and sinking-fund charges, while landed-property owners need a repair allowance for roofs, plumbing, wiring, gates, and exterior upkeep.
The monthly plan should also account for:
- Electricity, water, internet, and security
- Quit rent and assessment tax
- Fire or houseowner insurance
- Parking, access cards, and community charges
- Furniture, appliances, and periodic repairs
A separate emergency fund protects the deposit and moving budget from medical bills, job changes, or urgent home repairs. Buyers can use the emergency fund guide to set a reserve before directing every available ringgit toward the purchase.
From Budget to a Shortlist: What Should You Compare?
A useful shortlist compares the full cost and suitability of each home, not the advertised price alone. Buyers who want to buy a house in Malaysia should place properties within the approved budget, then assess tenure, location, condition, monthly charges, and loan readiness.
A spreadsheet makes differences visible. It should record the purchase price, estimated cash required, loan repayment, maintenance fees, travel cost, renovation allowance, tenure, built-up area, and inspection findings for every property.
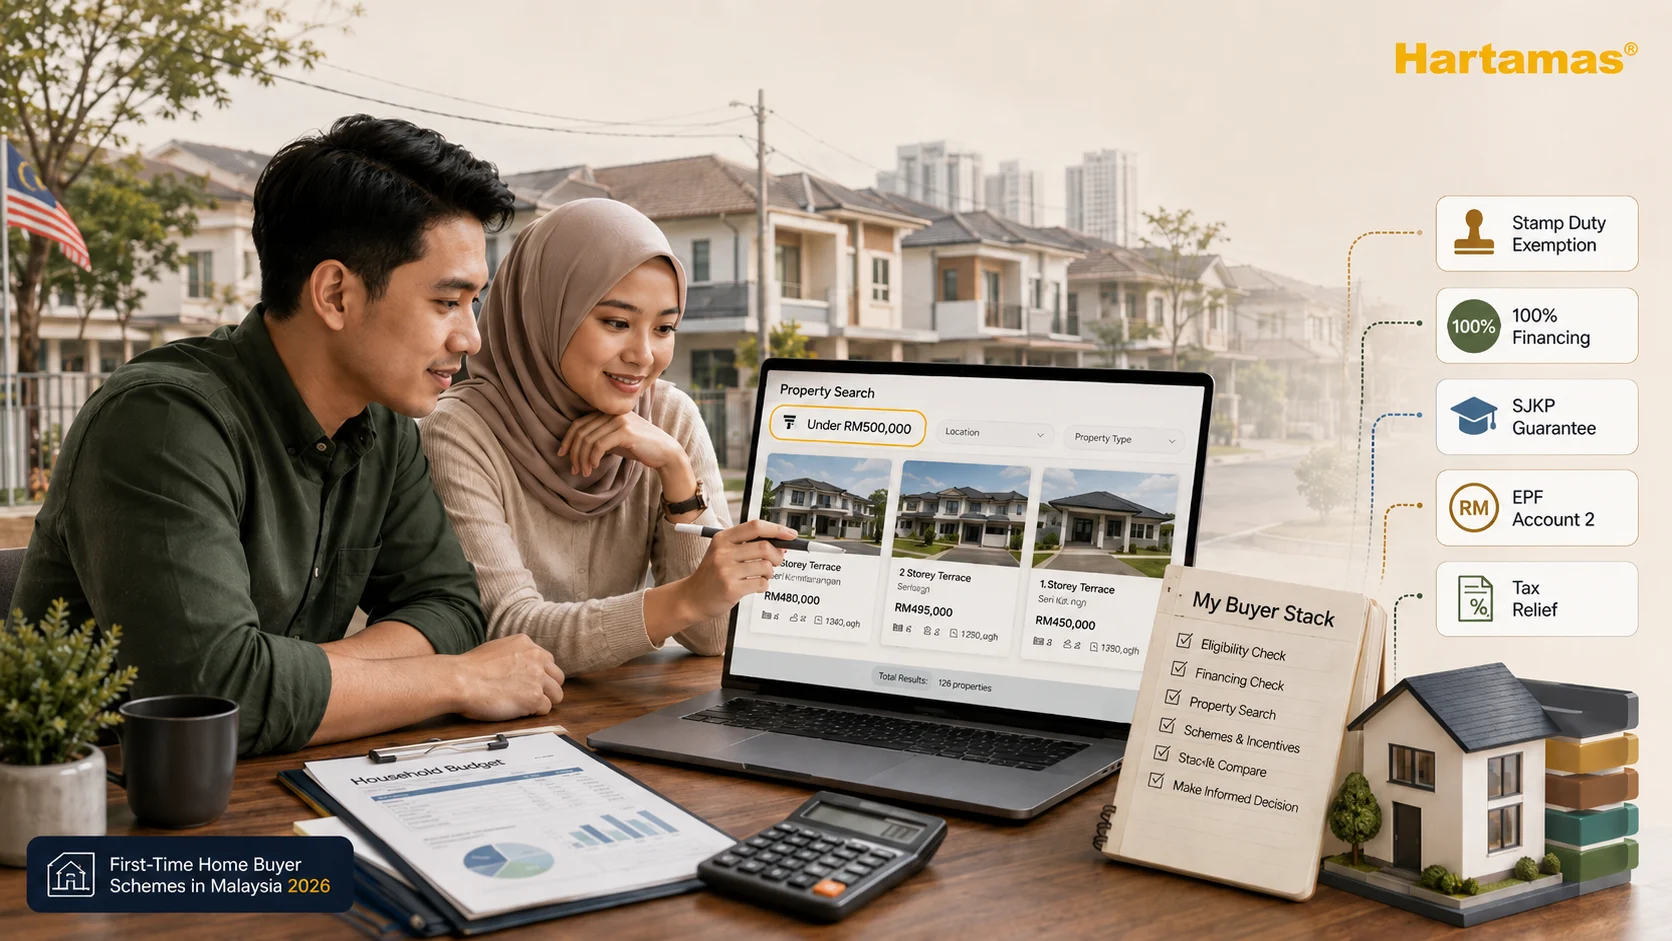
Choose Between New Launch, Subsale, and Affordable Housing
New launches may offer developer packages, staged construction payments, and modern facilities, with completion dates and progressive interest requiring close review. A buyer should inspect the developer’s track record, specifications, defects-liability terms, and the contract’s promotional conditions.
Subsale homes allow inspection of the building, neighbourhood, natural light, noise, water pressure, and surrounding traffic before purchase. They also require checks on outstanding charges, title details, renovation quality, tenancy status, and the seller’s completion timeline.
Affordable housing programmes can widen access through price limits, income criteria, location rules, ownership conditions, or resale restrictions. The schemes directory can help a first time homebuyer identify possible programmes, followed by eligibility confirmation with the scheme administrator and lender.
Compare Location, Tenure, Condition, and Monthly Charges
Location affects the household budget long after the keys are collected. Buyers should price daily travel, tolls, public transport, childcare access, schools, healthcare, flood exposure, and nearby development plans.
Tenure changes the legal and financing picture. Freehold and leasehold properties require review of title conditions, remaining lease, consent requirements, state authority processes, and lender policies. A low-priced leasehold home with costly renewal or resale constraints may fit poorly beside a slightly higher-priced property with clearer financing.
Condition should be assessed through a physical inspection, including dampness, cracks, plumbing, electrical points, windows, roof areas, lifts, and common facilities. Monthly charges need confirmation from the management body, including current maintenance fees, sinking-fund contributions, arrears, and planned special levies.
Check Loan Eligibility Before Paying a Booking Fee
A buyer should obtain a realistic loan assessment before paying a booking fee. Pre-qualification is an early estimate, while formal approval depends on documents, credit history, property valuation, legal status, and the lender’s final review.
The buyer should compare interest-rate structure, lock-in period, early-settlement terms, flexi features, insurance requirements, processing fees, and the consequences of missed payments. The bank should receive accurate information about income and liabilities, since overstating affordability creates problems during approval.
A booking form needs careful review of refund terms, financing conditions, the validity period, and what happens if the loan is rejected or approved for less than expected. The buyer should have the lawyer review the document and confirm the payment recipient before transferring funds.
Use Your Budget to Make a Confident First Purchase
A confident first purchase follows a clear sequence: set the maximum repayment, calculate cash requirements, keep an emergency reserve, compare suitable properties, and confirm loan eligibility before commitment. That process gives a first time home buyer malaysia a practical boundary for every viewing and negotiation.
First Home works well as a planning companion because its calculators, cost information, financing guidance, and scheme resources bring separate decisions into one starting point. Buyers should still verify figures with their bank, lawyer, developer, management body, and the relevant government programme.
The final choice should leave capacity for daily expenses, future repairs, and changes in income. Once the numbers remain comfortable after those checks, the buyer can proceed with a property that fits the household’s finances and living needs.